For decades, live sports has been one of advertising’s most exclusive environments. The audience is large, the attention is concentrated and the inventory is scarce. That combination has traditionally made sports advertising the territory of national brands with substantial budgets, direct relationships with networks and media teams sophisticated enough to navigate a complicated buying process.
Streaming is changing that equation. The next important development in sports advertising may not be another streaming service or another piece of audience data. It may be something more fundamental: making premium live sports inventory genuinely biddable.
The market is already moving in that direction. According to the Interactive Advertising Bureau’s 2026 Digital Video Ad Spend & Strategy Report, U.S. digital video advertising is expected to surpass $80 billion in 2026, growing 11% year over year and accounting for more than 60% of total TV and video ad spending for the first time. IAB specifically points to the migration of major sports rights to streaming, including NBA games on Amazon, NFL games on Peacock and Netflix, and MLB across multiple platforms.
That shift matters because streaming was built around a fundamentally different advertising model.
Linear television traditionally sells audiences through predetermined programming, dayparts and negotiated commitments. Programmatic advertising starts with the audience and the impression. A buyer can define who they want to reach, where they want to reach them, how frequently they want to reach them and how much they are willing to pay.
That model is increasingly moving into premium video.
The opportunity becomes particularly interesting when you look at who is driving the change. IAB reports that targeting has overtaken content quality as the top criterion for TV and video investment, with small and midsize advertisers showing a particularly strong increase in the importance they place on targeting. For those advertisers, the ability to buy premium content based on the audience they actually want could fundamentally change the economics of sports advertising.
Consider a regional automotive dealer that wants to reach sports fans in three specific markets. Or a restaurant chain looking to reach households watching a particular league. Or a national brand that wants to reach viewers with an established interest in a team without paying to reach every household watching the broadcast.
That is where biddable sports inventory becomes interesting. Premium inventory should retain its premium value. The goal is to give more advertisers access to the environment while allowing them to make smarter decisions about which impressions they actually want to buy.
There is already evidence that advertisers expect this level of control from streaming. The IAB’s 2026 research shows that as video spending has grown, buyer demands for quality, transparency and audience information have grown with it. The industry is moving toward a model in which simply delivering impressions is no longer enough. Buyers want to understand the quality of those impressions and the path their dollars took to get there.
Sports has another advantage: context.
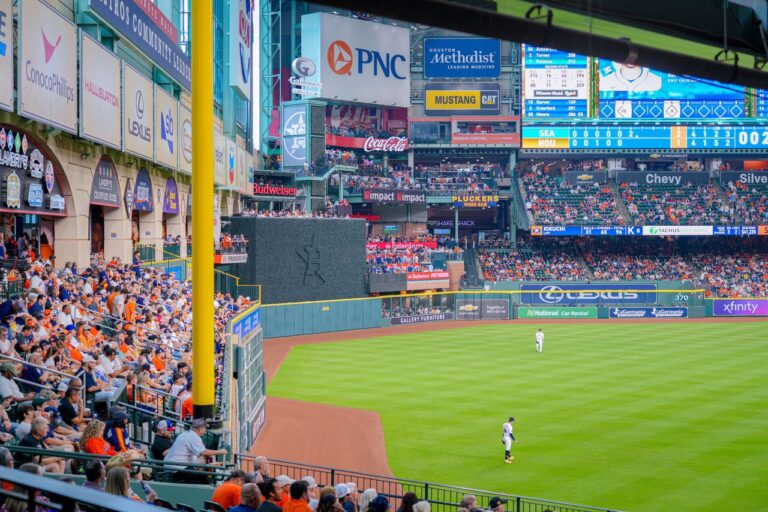
A viewer watching a live baseball game is giving advertisers information that goes beyond basic demographics. The league, team, game, geography and viewing environment can all become meaningful inputs into a media strategy.
That is particularly valuable as sports audiences become increasingly fragmented across streaming services. Deloitte’s research found that 53% of sports fans surveyed had paid for a streaming video service to access sports content during the previous year. At the same time, 62% said they were frustrated by difficulties finding sports content, while 54% said they had actually missed events they wanted to watch because of those difficulties. Deloitte’s research on the future of sports streaming illustrates the fundamental challenge: the audience is there, but reaching it efficiently is becoming more complicated.
Advertising faces a similar fragmentation problem.
A buyer may have access to premium sports inventory through multiple publishers, streaming platforms, SSPs and private marketplaces, each with different deal structures, audience signals and measurement capabilities. Simply putting more sports inventory into a DSP does not solve that complexity. It can actually create more of it.
The real opportunity is to build a cleaner supply path around premium sports.
That means curating inventory, enriching it with meaningful signals and packaging it in ways that make sense for the buyer’s objectives. As Splash Bay Media’s own work around programmatic media buying illustrates, the DSP is only one part of the equation. What happens to inventory before it reaches the DSP can have a significant impact on what the advertiser ultimately buys.
The same principle applies to CTV. Programmatic television buying can give advertisers more flexibility, targeting and measurement than traditional linear buying, but those advantages depend on the quality of the inventory and the transparency of the supply path behind it.
That is where the next generation of sports advertising has an opportunity to differentiate itself.
The industry does not need to choose between premium sports and programmatic efficiency. It can combine the two.
If streaming has taught the advertising industry anything, it is that premium television does not have to mean inflexible television. The next phase of sports advertising should preserve the quality and scarcity that make live events valuable while giving buyers the precision, transparency and flexibility they now expect from digital media.
Premium sports have always been valuable. The real advance will come when we make that value easier to buy.