
Silicon Valley has spent decades perfecting the art of creating equity.
Figuring out what to do with it before an IPO is proving more complicated.
The traditional startup bargain was relatively simple: join early, take equity, help build something valuable, and wait for the exit. Investors played a version of the same game. The IPO, or an acquisition, was the moment years of illiquid ownership finally turned into something tangible.
That bargain looks increasingly outdated when successful companies can remain private for 10, 15, or even 20 years.
A startup can now become a multibillion-dollar business without ever ringing an opening bell. Employees can accumulate substantial equity. Early investors can sit on major unrealized gains. Founders can build companies operating at a scale once associated primarily with the public markets.
The value is being created. Access to it hasn’t kept pace.
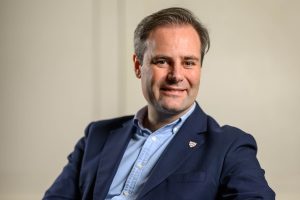
“An IPO should be a strategic choice, not the price a company has to pay for liquidity,” says Tomas Milar, founder and CEO of equity management and valuation platform Eqvista. “If staying private longer is the new reality, the financial infrastructure around private ownership has to catch up.”
And that may be the more interesting story. The problem isn’t simply that private companies need another way to sell shares. It’s that a market built around waiting for an exit is colliding with a world in which the wait itself has fundamentally changed.
When Paper Wealth Stays Paper
Nowhere is that tension more personal than employee equity.
Stock options remain one of the startup world’s most powerful recruiting tools. They offer employees something a salary alone cannot: ownership in the upside they are helping create.
But ownership gets more complicated when the exit keeps moving further away.
“An employee can spend eight years helping build a company and have $500,000 of equity on paper,” Milar says.
Then comes the line that cuts through most of the financial jargon: “That’s exciting, but you can’t buy a house with a cap table.”
The point isn’t that illiquid equity is worthless. Far from it. The problem is that the longer it remains inaccessible, the harder it becomes to treat that value like ordinary wealth.
“The longer companies stay private, the harder it becomes to ask employees to treat equity as a meaningful part of their compensation without better visibility into what it is worth and a credible path to eventually realizing some of that value,” Milar says.
That creates an obvious temptation: make private shares easier to trade.
But more trading introduces another problem.
Liquidity Is Only Useful If Anyone Knows the Price
“Liquidity without price discovery is just faster uncertainty,” Milar says.
That distinction gets surprisingly little attention in the rush to democratize private markets.
A public company’s share price is continuously tested by buyers and sellers. Private-company pricing can be anchored to a funding round that happened 18 months ago, even if nearly everything relevant to the business has changed since.
Revenue may have doubled. Growth may have stalled. Interest rates may have moved. A competitor may have raised at an eye-watering valuation or imploded entirely. An entire category can fall in and out of favor while the last headline valuation remains frozen in time.
“The industry loves talking about liquidity, but trading is the second problem. Pricing is the first,” Milar says. “Public markets have a shared reference point for price. Private markets largely don’t.”
That is the problem Eqvista is trying to attack with its Real-Time Company Valuation. Milar says the company’s models continuously value more than 45,000 private companies representing approximately $9 trillion in private-market value, creating something closer to a continuously updated reference point for private-company value.
The broader argument matters beyond any one platform. If private markets want more liquidity, they first need more confidence in the information underpinning a transaction.
“More transactions alone do not create a healthier private market,” Milar says. “Better information, better price discovery and better-managed liquidity do.”
In other words, adding more doors doesn’t help much if buyers and sellers still disagree about what’s behind them.
More Liquidity Isn’t Necessarily Better Liquidity
Price isn’t the only complication.
Private companies stay private partly because they value control. Founders generally care who owns their shares, how much changes hands, and when those transactions occur. Opening up liquidity without preserving that control can solve one problem by creating another.
Milar argues that founders shouldn’t have to choose between two extremes.
“Founders should not have to choose between locking shareholders up indefinitely and turning their cap table into the Wild West,” he says. “A company should be able to decide when liquidity happens, who can participate, how much equity can be sold and who is allowed onto the cap table.”
His shorthand for that model is more useful than the usual promise of simply making private markets “more liquid.”
“The goal isn’t maximum liquidity. It’s intelligent liquidity.”
That changes the question. Instead of asking how private shares can trade more like public stocks, the better question may be how liquidity can work differently precisely because the company is private.
The Private Market Is Becoming Its Own Destination
None of this makes the IPO obsolete.
Going public can still provide access to capital, liquidity, and visibility that private markets cannot fully replicate. But it increasingly looks like one option in a company’s lifecycle rather than the inevitable conclusion to it.
That requires a different way of thinking about the infrastructure underneath private ownership.
“Private markets are becoming a destination in their own right, not simply a waiting room for public markets,” Milar says.
If companies are going to spend a decade or longer in that destination, the systems supporting them need to do more than keep track of who owns what while everybody waits.
“The next generation of private-market infrastructure needs to connect three things that have historically been treated separately: ownership, valuation and liquidity,” Milar says.
That may ultimately be the bigger challenge facing private markets. Creating equity was the easy part. The startup ecosystem has become extraordinarily good at distributing ownership across founders, employees and investors.
Now it has to figure out how that ownership actually functions when “wait for the IPO” is no longer a sufficient answer.
As Milar puts it: “We’ve spent decades getting very good at creating private-company equity. The next challenge is making that equity actually work while companies remain private.”